

Gold tops USD 3,000 and trade-war fears intensify, but no panic
Although the sweeping changes Trump has imposed on markets add uncertainty, the message is clear: a downturn may be on the way, but this is not the time to panic.
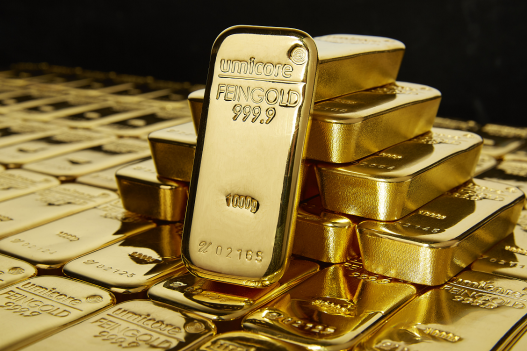
Last Friday, gold reached the key USD 3,000 mark for the first time ever, driven by escalating fears of a trade war and rising expectations of a rate cut by the Federal Reserve, after setting an all-time high on Thursday. Investors continue to favour gold as a safe haven as economic and geopolitical uncertainty grows.

Wall Street slumped on Thursday as Trump's intensifying trade war rattled investors, pushing the S&P 500 into a 10.1% correction from its February peak. The Nasdaq is also in correction territory, and the Dow Transport index is nearing bear-market levels. The latest blow came after the EU imposed a 50% tax on American whiskey, prompting Trump to threaten 200% tariffs on European wine and spirits. US inflation fell to 2.8% in February, below expectations, offering some relief amid trade-war concerns. Core inflation, which excludes food and energy, also slowed to 3.1%, its lowest level since April 2021. Despite the positive data, uncertainty remains high because of the tariffs, which could push prices higher in the months ahead. The Federal Reserve is expected to keep interest rates unchanged next week, but markets are pricing in rate cuts starting in June if inflation keeps easing.
European markets also ended lower on Thursday, when Trump's threat to impose 200% tariffs on EU wines and spirits sent alcohol stocks tumbling. Pernod Ricard, Rémy Cointreau and Campari fell by more than 3%, while LVMH lost 1.1%. The Stoxx 600 closed down 0.15%, with automotive stocks leading the decliners (-1.7%), as investors weighed possible retaliatory measures from the EU and Canada.
Recession risk is rising, but no panic. J.P. Morgan chief economist Bruce Kasman warns that the probability of a recession in the United States this year is 40%, up from a previous estimate of 30%. Kasman cited Trump tariffs and political uncertainty among the reasons. If reciprocal tariffs come into force in April, the risk could even exceed 50%. Kasman also warns that the unpredictability of US policy could weaken investor confidence in American markets, threatening the "exorbitant privilege" that allows the United States to finance its debt cheaply. These are, however, forecasting indicators that still need to be tested against reality, and the facts prevent us from being even remotely "catastrophists". Despite the economic uncertainty, the markets are pointing only to a slowdown, not a lasting and broad-based economic crisis.
As for the bond market, spreads on US corporate bonds have risen to their highest level in six months, reflecting growing recession fears. Investment-grade bond spreads have reached 94 basis points, while high-yield bonds (junk) have hit 322 basis points, signalling greater risk aversion. Yet possible Fed rate cuts should produce the opposite trend, suggesting that this monetary-policy forecast is not fully priced in. Equities have fallen, pointing to slower earnings growth, but credit spreads remain stable, showing confidence in corporate debt.
Therefore, although President Trump's sweeping policy changes add uncertainty, the market message is clear: a downturn may be coming, but this is not the time to panic. In fact, markets attempted a rebound last Friday, so bulls will probably want to see more than a one-day bounce to build confidence. There are also several potential market-moving catalysts next week, including Monday's monthly retail sales report, a FOMC meeting on Tuesday-Wednesday and Nvidia's annual GTC conference, which runs throughout the week. In the current environment, there is also the possibility of updates on tariffs, which could be either escalatory or de-escalatory in nature.
In addition, several technical indicators have flashed oversold conditions, but that was also the case last week. There is some uncertainty around the retail sales report, but also curiosity about whether the stock market will react negatively if the report comes in weak. As for the Fed, given the relatively benign inflation data and further evidence of an economic slowdown, Fed Chair Powell will likely strike a more dovish than hawkish tone with markets. Therefore, the forecast for next week is bullish again, and Friday's "technical rebound tests" may have more room to play out. What could challenge this outlook? If we get further tariff escalations next week, markets could switch back to risk-off mode and turn lower.
Tags
Related articles


Newsletter
The Patrimoni & Finanza newsletter
A considered selection of analysis on economy, Real Estate and wealth
The subscription service is not connected yet: no address is stored