
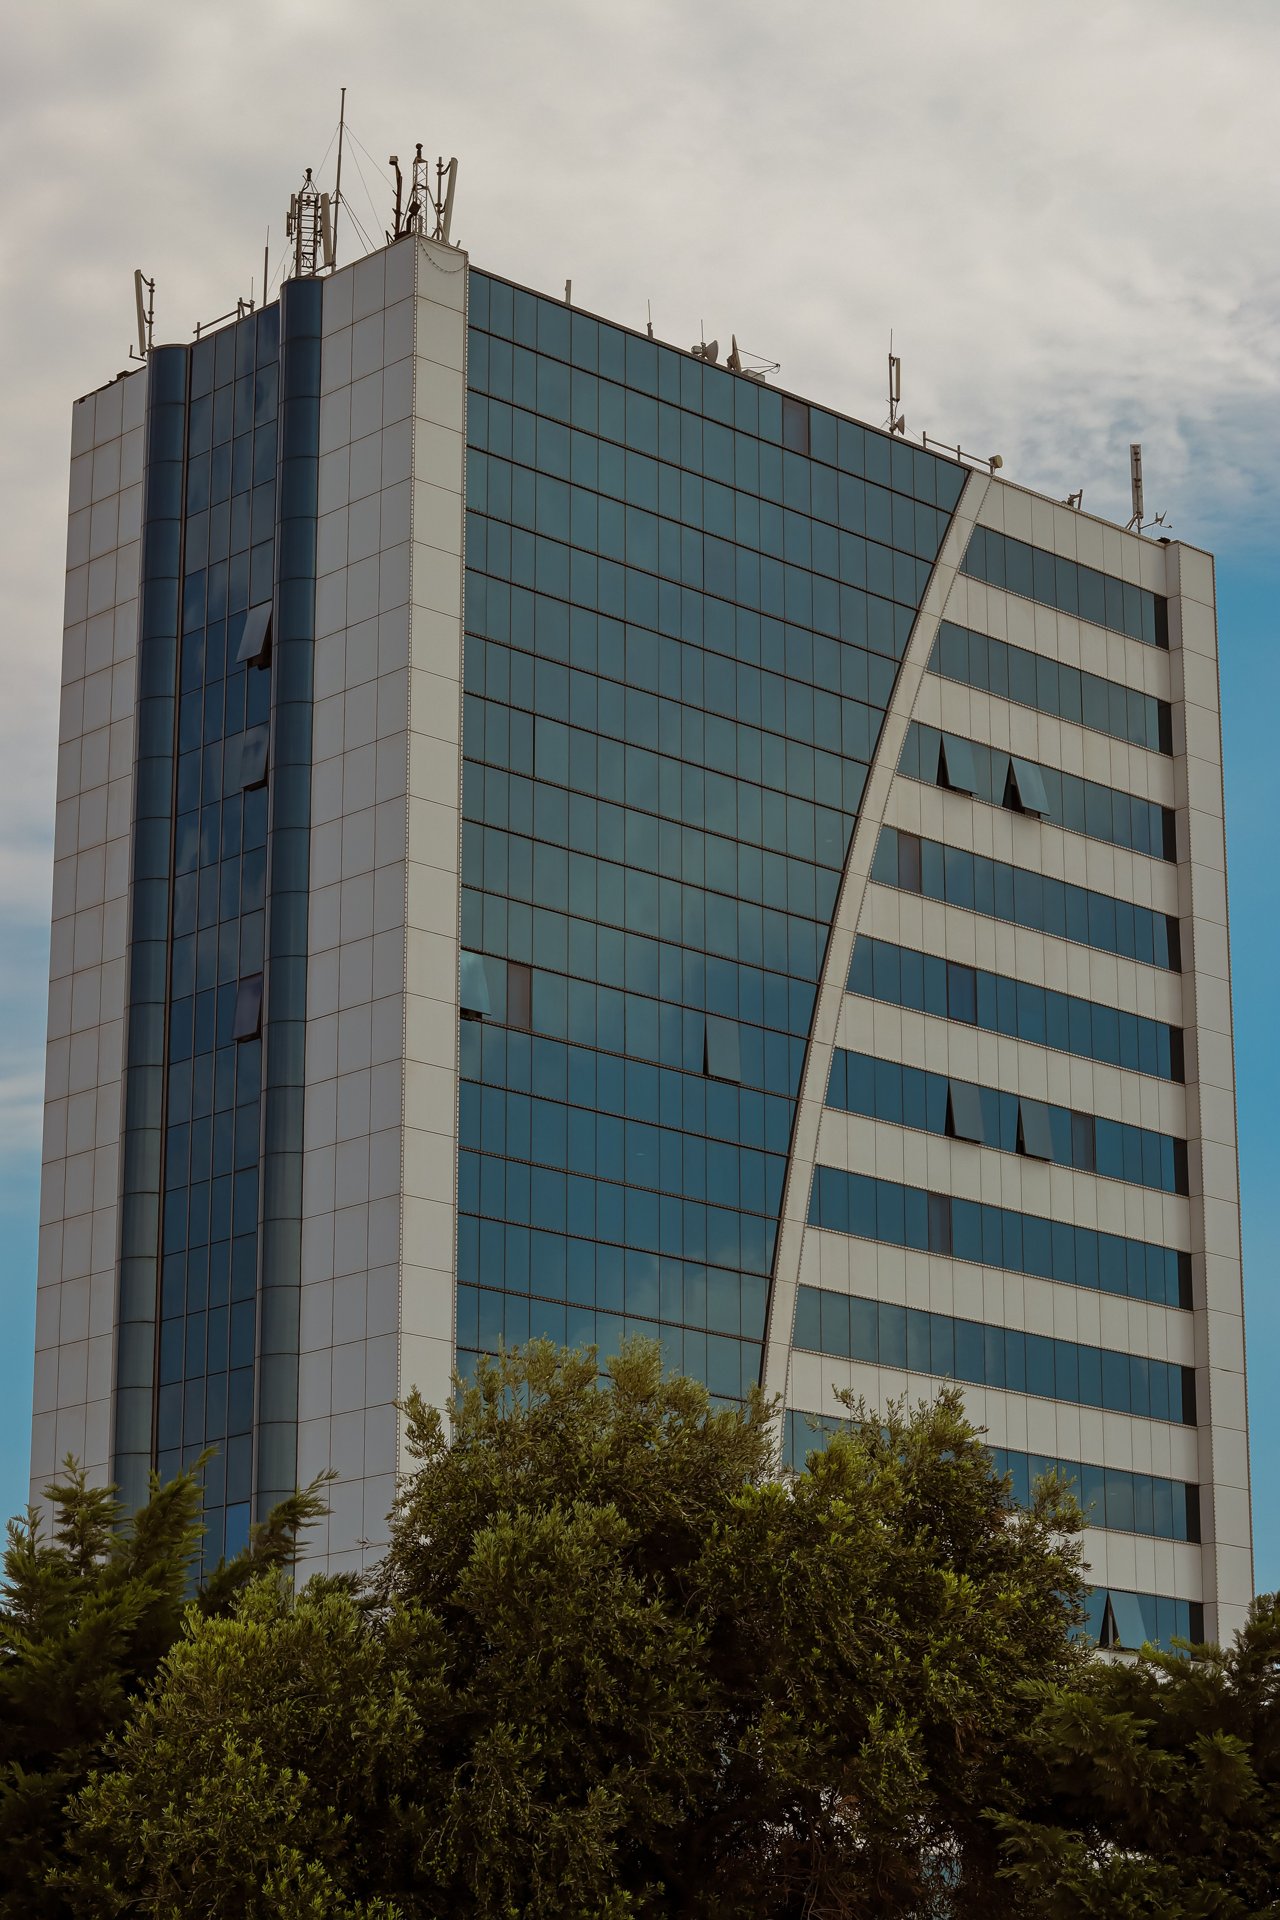
Commercial property towards 2027 why capital is becoming more selective
The Deloitte report describes a sector that continues to invest, but increasingly distinguishes between buildings to refurbish, properties to convert and assets to exit. Logistics, digital infrastructure and tenant quality are changing how returns are assessed
The market beyond shops and offices
A commercial building may still physically exist yet already have lost a significant part of its economic usefulness, because its spaces no longer meet businesses’ needs, energy consumption makes it expensive to run or its location cannot support the rents needed to generate a return on the capital invested; this gap between property and function is a useful starting point for reading Deloitte’s 2027 Commercial Real Estate Outlook, published on 24 September 2026. The report describes a market in which money continues to seek opportunities, but is unwilling to fund every project indiscriminately, while value increasingly depends on the owner’s ability to demonstrate demand, sustainable costs and the feasibility of works. For Italian readers, accustomed to associating property primarily with housing, commercial real estate encompasses a broader universe of properties intended for economic activities and professional investment, from offices to warehouses and hotels, through to the infrastructure supporting the digital economy; the study’s interest lies in showing how these categories can go through different phases, even within the same city.
The Deloitte Center for Financial Services survey gathers the views of 950 executives and their direct reports at property owners and investment companies with at least 250 million dollars in assets under management, interviewed between June and July 2026 in North America, Europe and Asia Pacific; Italy is not among the European countries in the sample, which includes France, Germany, the Netherlands, Spain and the United Kingdom. It therefore offers an insight into the strategies of established operators, rather than a specific forecast of Italian prices or a survey of small landlords, and the responses mainly concern the following twelve–eighteen months. This clarification is necessary to interpret the figures correctly, because a major investor’s expectations can help direct capital and market standards without automatically describing the fate of an individual shop or a provincial office; applying the conclusions to the Italian context requires checking local demand, contractual terms and the availability of credit, without confusing an international preference with a recommendation to buy.
The first message is that caution and confidence in revenue coexist: respondents’ overall confidence index falls to 57,8 points out of 100, from 64,9 in the previous survey, yet 51% still expect revenue growth of more than 5%. This is not necessarily a contradiction, because a company can forecast an improvement in its income while limiting new investment, selecting projects more rigorously or protecting liquidity, particularly when the cost of capital makes it harder to correct a mistake. The editorial interpretation is that any recovery will not be enough to lift every property portfolio equally: a well-positioned portfolio can improve even in a weak environment, while an outdated building can lose competitiveness despite rising sector revenues. For owners, this means assessing a property as an economic activity with its own customers, costs and deadlines, rather than viewing it as a store of value destined to appreciate simply with the passage of time.
Refinancing can change value
The cost and availability of capital, together with interest rate levels, remain the main macroeconomic concerns cited by respondents, while maturing loans require a comparison between debt taken on in the past and the terms on which it might be renewed. The risk is not confined to repayments: when the property’s income does not grow sufficiently, a bank may require more equity capital, reduce the loan or impose tighter conditions, forcing the owner to choose between fresh contributions, a sale and revising the project. In economic terms, a letting that appeared satisfactory with inexpensive financing can become insufficient even though the tenant has not stopped paying, because the cost of supporting the investment changes. Analysis should therefore cover the expiry dates of leases and loans, anticipated expenditure on works and remaining liquidity in a less favourable scenario; gross rent, considered in isolation from these factors, tells only part of the risk story.
A purely illustrative example makes the mechanism clear: if a property generates 100.000 euros a year in net operating income, a valuation obtained by capitalising that income at 5% would be 2 million euros, whereas at 6% it would fall to around 1,67 million, even with income unchanged. This is neither a Deloitte forecast nor a valuation, since actual value depends on many other variables, but a way of understanding why an increase in the yield required by investors can reduce the price they are willing to pay. If works are also needed to maintain occupancy, the problem is amplified, while credible income growth may offset it only in part. The return must therefore be examined alongside the quality of the cash flow and the capital still required, distinguishing an apparently attractive price from a property carrying unrecognised expenditure: buying at a discount is not enough if the work needed to make the asset competitive absorbs that advantage before the new tenancy even begins.
The geographical preferences identified in the report place the United States, the United Kingdom and India among the main overseas destinations under consideration, while the picture described for continental Europe is affected by a less uniform recovery and sensitivity to the cost of borrowing; this does not mean that an Italian investment is destined to be less attractive, but that it will have to compete with alternatives assessed on an international scale. An investor may compare a warehouse in Italy with a transaction in another country by considering currency, taxation, financing and exit options, rather than focusing solely on the first year’s return. For those selling or seeking a partner, the practical consequence is to prepare consistent, verifiable information on operating income, tenants’ positions and future commitments, because undocumented uncertainty tends to translate into a discount demanded by the buyer. The stability of permissions and clarity of documentation also become economic components of the transaction, since they reduce the risk of committing capital for months without being able to launch the project.
Refurbishment does not mean spending regardless
Almost 80% of respondents expect to upgrade or reposition properties over the following twelve–eighteen months, with 38% reporting particularly intensive activity, but the report also records reluctance to realise losses: 39% do not anticipate conversions and 46% are not planning sales. Deloitte proposes examining portfolios property by property, distinguishing between works, retention, conversion and disposal, rather than allocating resources uniformly. This matters because refurbishment creates value only when demand can support a sufficient premium, while costly works on a building with structurally weak demand may postpone the loss without resolving it. For an Italian owner, the first assessment should therefore be commercial rather than aesthetic: which occupiers might choose those spaces, on what terms and with what continuity, once the cost of the works has been incurred; design quality remains necessary, but is no substitute for a market willing to pay to use it.
In offices, the difference between a modern building and a poorly functioning property can translate into a different ability to retain tenants, because flexible layouts, comfort and operating costs all enter the comparison with alternative premises; in logistics, meanwhile, the assessment must include accessibility, the organisation of flows and the suitability of spaces for the activities they accommodate. The report ranks logistics and warehouses among the preferred opportunities, followed by properties serving the digital economy, but this hierarchy does not make all assets bearing the same label interchangeable. A warehouse unsuitable for an occupier or a digital site lacking the necessary infrastructure does not acquire quality simply because it belongs to a fashionable category, while converting a building to a different use requires specific technical and regulatory checks. The editorial analysis is that competitive advantage is shifting from simply owning square metres to being able to offer them in the form actually required, including the risk of works extending beyond the period in which the market rewards that solution with a premium.
An interesting signal concerns neighbourhood retail, which moves from eleventh to fifth place in the ranking of opportunities, while hotels and accommodation facilities fall from eighth to thirteenth: these are the sample’s preferences, not forecast price changes or a rejection of every hotel. The report links the improvement in neighbourhood shops to limited space availability and resilient occupancy, but applying this finding requires an examination of the tenant’s business and the shop’s actual catchment area. Premises supported by recurring demand may serve a different function from those dependent on occasional footfall, while a prestigious location can lose profitability if the rent exceeds the financial capacity of the business occupying it. Likewise, in the case of hotels, a global ranking does not eliminate quality opportunities in Italy: rather, it suggests that competition, customers’ sensitivity to prices and operating costs require closer assessment of individual transactions and caution against automatically extrapolating from the results of the best years.
Taxation technology and responsibility
Taxation enters the investment process before signing, according to the approach outlined by Deloitte, because the return that matters to capital is what remains after taxes, charges and the constraints of the chosen structure; more than 60% of the sample expect to direct resources towards jurisdictions or activities with more favourable incentives, but this does not mean that tax relief can make a project without demand sustainable. For an Italian investor, the lesson is to assess the tax implications of acquisition, management and exit early, without incorporating benefits available under foreign legal systems or incentives that have merely been announced into their own plan. Even potential savings must be weighed against timing, requirements and certainty of use, because a benefit that cannot be accessed when cash flows are needed may leave funding requirements uncovered. The project should remain understandable and defensible even when its underlying business performance is separated from tax support, so that it is clear which part of the return comes from the property and which depends on regulatory conditions that could change.
Artificial intelligence is the other area in which the report calls for greater discipline, indicating that 72% of the sample have completed an initial data-mapping exercise and source verification, while fewer than half have adopted more advanced process and security controls. The point is not simply to produce an estimate quickly or compare listings, but to know what information has been used, who can access it and who is accountable for a wrong decision, particularly when tools influence tenant selection, pricing and the allocation of capital. Duplicate data, an expired contract interpreted as active or a floor area that is not comparable can make an analysis based on flawed foundations appear convincing, while automation can multiply its effect before anyone notices. The benefit for a property company therefore comes not from the number of tools adopted, but from the ability to use them within controllable processes, in which documentation, oversight and accountability remain proportionate to the economic significance of the decision.
The study’s concluding message is that 2027 could reward those able to differentiate and act, rather than those waiting for a general recovery or increasing expenditure indiscriminately, and it also concerns the preparation of the people responsible for managing portfolios: the ability to interpret data and technology must sit alongside property expertise and operational judgement. For Italian readers, commercial real estate thus emerges as an investment in the functioning of a business and the quality of the contractual relationships supporting it, even before the physical substance of an asset. The most useful question is not whether the sector will rise or fall as a whole, but whether that particular property will be able to generate income after the works, financing and expenditure needed to keep it competitive; when the answer requires excessively favourable assumptions, the advertised return may simply measure the risk being taken. When demand, costs and alternatives are documented, however, the selectivity of capital can become an opportunity for those able to recognise neglected but still economically useful assets.
Tags
Related articles


Newsletter
The Patrimoni & Finanza newsletter
A considered selection of analysis on economy, Real Estate and wealth
The subscription service is not connected yet: no address is stored