
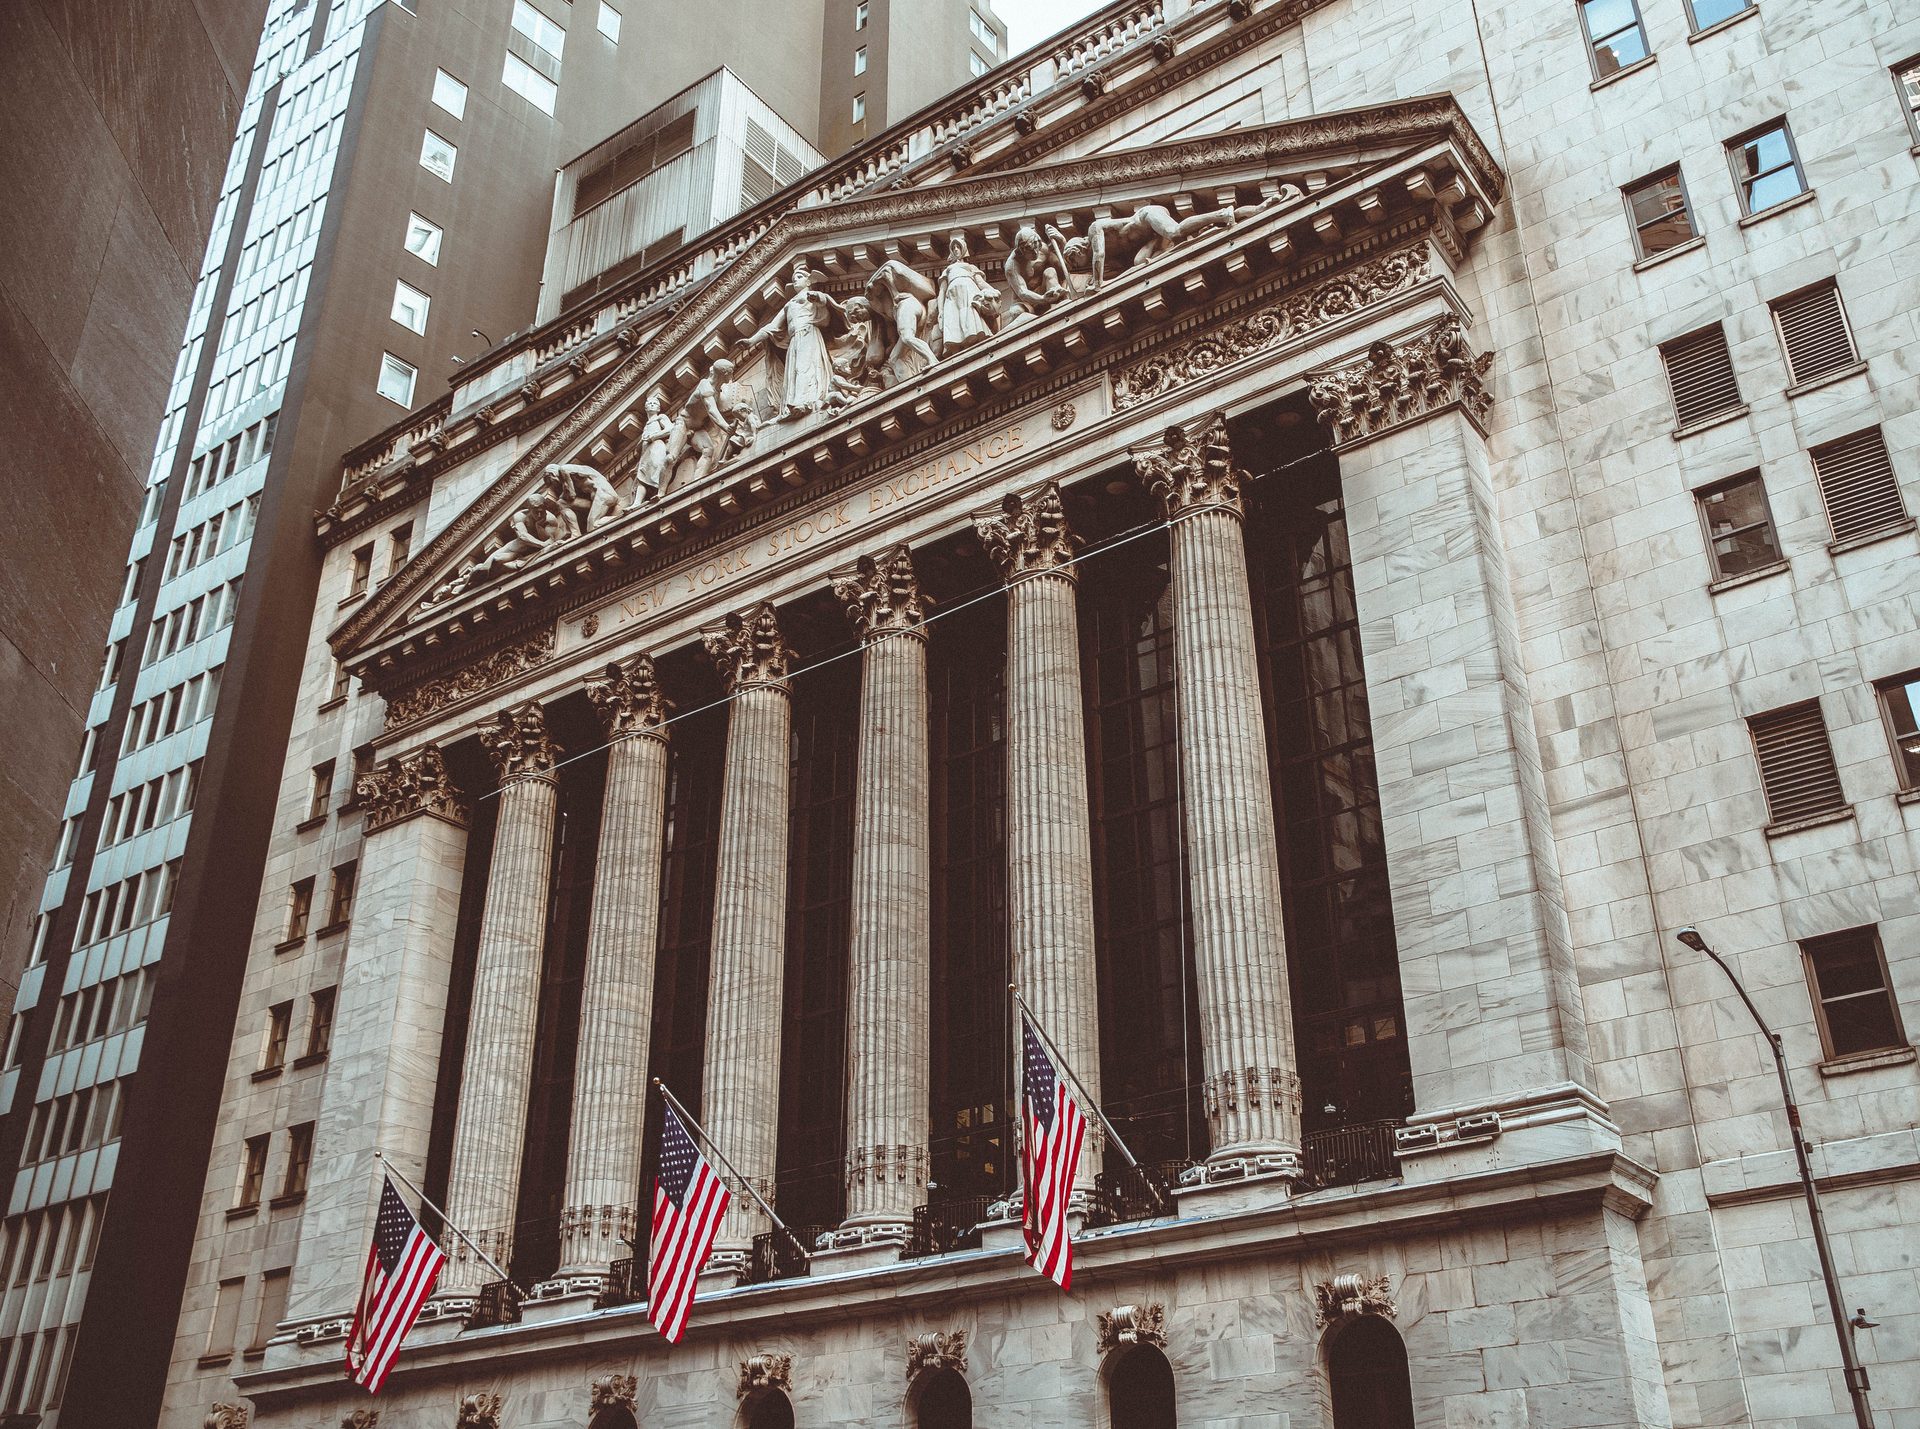
The concentration of wealth and financial power betray the Western social compact
The Western social compact was built on a promise: that through commitment and work it would be possible to improve one’s circumstances and ensure a better life for one’s children. Today that promise appears broken, especially for young people
According to the World Inequality Report 2026, the richest 10% of the world’s adult population owns about 75% of wealth, while the poorest half is left with just 2%. It is a global figure that does not on its own describe the situation of the Western middle class, but it shows how concentrated wealth is.
Meanwhile, families are struggling to buy a home, save and build financial security. In this scenario, the weight of the major financial players also comes into focus. BlackRock, Vanguard and State Street manage enormous assets and, through the funds they run, hold significant stakes in the largest listed companies.
According to a study by IESE Business School, the three managers are among the five largest shareholders in 90% of S&P 500 companies. This does not mean they directly control governments or personally own the capital they manage. But their presence raises an important question: how much room do political decisions still have when such a large share of the economy depends on financial markets and major institutional investors?
Western countries, now France and the United States too, under the growing weight of debt
Public borrowing is also becoming increasingly significant. In France, according to INSEE, public debt reached 3,595.5 billion euro in June 2026, equal to 119% of GDP. The need to contain the deficit clashes with the demands of citizens calling for greater social protection and adequate public services while the government invests in war and armaments. In the United States, gross federal debt has climbed above 40,000 billion dollars. For 2026, the federal deficit was in the region of 2,000 billion, with annual net interest costs above 1,000 billion.
These are very different economies: in particular, the international role of the dollar gives the United States advantages that France does not enjoy to the same extent. But the common issue is clear: a growing share of public resources has to contend with the burden of debt, while the demand for economic and social intervention continues to rise, even as plans are made to reduce it. And the problem concerns future generations above all. In the United States, according to the National Association of Realtors, in 2025 the median age of first-time homebuyers reached 40.
Public debt is not necessarily a negative legacy: if it finances infrastructure, education and productive investment, it creates lasting opportunities. If, on the other hand, it rises without supporting adequate growth, it limits the prospects of the generations that follow. What confidence can young people have in the future when they face ever greater difficulty in building a profession, a home, a prosperous future, while inheriting such a high level of public debt?
The relative decline of the West and the rearmament dilemma
Added to domestic difficulties is an international transformation. China’s growth, India’s weight and the expansion of BRICS show the determination of several emerging economies to strengthen their international standing and generate prosperity for their citizens. The so-called Global South is not currently a homogeneous bloc, but its key players are challenging the trade and financial balances that have favoured Western dominance. The West must therefore face greater international competition precisely as it struggles to respond to the economic and social demands of its citizens.
In this context, the delicate chapter of rearmament opens. With the ReArm Europe/Readiness 2030 programme, the European Union intends to mobilise up to 800 billion euro in additional defence spending capacity, through financing tools and fiscal flexibility. The move is justified by new security needs, the war in Ukraine and uncertainty over the geopolitical balance.
However, a political and economic question arises: how can the budget constraints invoked for welfare be reconciled with the willingness to expand military investment? In a Keynesian perspective, military spending can also support demand, production and employment. It generates orders for defence companies and opportunities for investors, but it entails public costs and may require new borrowing.
It is nevertheless legitimate to ask who really benefits economically and how the costs are distributed.
What resources will be available for healthcare, education and social policies? What debt will we leave to the younger generations?
History also shows that, in times of domestic difficulty, the perception of an external threat has often been used to temporarily strengthen support for governments. This does not prove that conflicts are always provoked to distract citizens. But it does call for vigilance, so that security choices do not replace debate on economic and social difficulties.
The crisis of consent and a possible way forward: investing in the person
The philosopher Andrea Zhok notes that a population does not need to sink into extreme poverty in order to lose trust in institutions. It is enough for the living conditions and prospects it had reason to expect to disappear. The protests sweeping the West today have different causes. Acts of violence must be condemned, but they cannot be used as an excuse to ignore peaceful calls for work, justice, education and a future.
Faced with this situation, one possible way to start again emerges from Pope Leo XIV’s encyclical Magnifica Humanitas. The dignity of every human being does not depend on the results achieved, the wealth possessed or the ability to produce. When everything is measured in terms of efficiency, the person risks becoming an instrument at the service of economic and power interests.
And what if the answer to the crisis were not simply to invest more in weapons, but to go back to investing in people? It would mean seeing education, decent work, human growth and relationships not as costs to be squeezed, but as fundamental conditions of development. Small entrepreneurs can also make a difference: the business must generate wealth, but it must also be a place where people grow, build relationships and take part in a shared ideal. This is not about setting the person against the economy or technology, but about recovering the purpose to which both must serve for the common good.
Perhaps the way out of this crisis runs precisely through here: rebuilding a shared ideal in which the value of the human being comes before economic interests and power returns to being a service to the person. Because, as Leo XIV reminds us, the quality of a civilisation depends not only on the power of its means, but on its capacity to care for people.
Power, increasingly concentrated on preserving itself and economic interests, has helped empty shared ideals, weakening identities and social bonds. When there is no positive ideal to build around, it becomes easier to identify an enemy around which to gather consent: confrontation replaces the common good and fear takes the place of hope. True progress, instead, is building a society in which every person can recognise their own worth and find the conditions to fulfil themselves.
Main sources
- Ray Dalio, Principles for Dealing with the Changing World Order
- World Inequality Report 2026, World Inequality Lab
- INSEE, data on French public debt, second quarter 2026
- U.S. Treasury, data on federal debt 2026
- National Association of Realtors, 2025 Profile of Home Buyers and Sellers
- European Commission, ReArm Europe/Readiness 2030
- Andrea Zhok, La pentola a pressione
Tags
Related articles

Newsletter
The Patrimoni & Finanza newsletter
A considered selection of analysis on economy, Real Estate and wealth
The subscription service is not connected yet: no address is stored